Can an S corporation owner opt out of Oregon unemployment tax?
A lot of owners pay Oregon unemployment tax on their own paycheck and never learn they had a choice. It is money out the door for coverage on a job you control, and one form could have prevented it.
Can an S corporation owner opt out of Oregon unemployment insurance?
Oregon taxes the pay of corporate officers and shareholders by default. The Employment Department says so in plain words: unemployment tax applies to amounts paid to corporate officers and shareholders. The exclusion is the exception, and you have to ask for it.
Picture a fictional Portland roofer who runs an LLC that elected S corporation status this year. For that owner the legal entity matters more than the tax election, and the state has not settled the case in writing.
The Employment Department's UI PUB 208 says an LLC is not liable for unemployment tax on pay to its members. The same publication says pay from an S corporation is treated like pay from any other corporation. It never says which rule wins for an LLC taxed as an S corporation.
So the answer is pending. We will update this page when the Employment Department answers. Until then, call its tax line at 503-947-1488 before you file anything.
Now picture an owner who formed a corporation instead. She is the only officer and director and owns all of it. That is the case Form 2578 was built for. Without it, she pays unemployment tax on her own salary, which buys coverage on a job she controls.
Who qualifies for the officer exclusion?
Two paragraphs of the statute matter. One covers officers who are directors, have a substantial ownership interest and are members of the same family. The other covers a sole corporate officer and director who has a substantial ownership interest. The rule behind them sets the ownership tests.
| Test | What the rule says |
|---|---|
| Statute | ORS 657.044 |
| Family officers | Directors with substantial ownership who are members of the same family |
| Sole officer | The only corporate officer and director, with substantial ownership |
| Substantial ownership | Each excluded officer owns at least ten percent (OAR 471-031-0017) |
| Combined ownership | The excluded officers together own at least seventy-five percent |
| Ownership accounted for | The form requires 100 percent of ownership to be accounted for |
Having an employee does not by itself rule you out. A helper on her payroll stays covered. The exclusion is for the officer, so a helper on payroll is not part of it.
When does the opt-out take effect?
The form also ties the earliest start date to the state's unemployment trust fund rate schedule. Read that line on the form, and let the approval letter tell you the quarter that applies to you.
How do I file Form 2578?
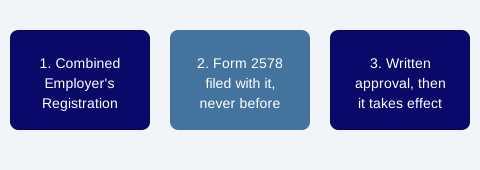
File it in writing with the Employment Department, Tax Section, 875 Union Street NE, Salem, Oregon 97311-0030, or by fax at 503-947-1700. File it together with your Combined Employer's Registration, never before it, because the state processes the two forms at the same time.
- Register as an employer with the Combined Employer's Registration, as you did for your Oregon BIN.
- File Form 2578 so it arrives with that registration. The Employment Department says a request cannot come before the registration and that it processes both at the same time.
- Wait for the written approval. Do not assume the exclusion started because you mailed the form.
- Put the approval letter in your files.
What happens if ownership changes?
The election ends if a change in ownership means the officers no longer meet the tests. It ends on the date of the change, even if the department hears about it later. The form also says the corporation must notify the department in writing within 30 days of an ownership change.
A new partner, a stock gift to a child, or a sale of shares can all be that change. This is why the minutes matter. Add a line the day any of it happens.
Does opting out of Oregon unemployment tax end federal unemployment tax?
The federal rate is 6.0 percent on the first 7,000 dollars of each employee's wages. The IRS says you may receive a credit of up to 5.4 percent if you paid state unemployment tax in full, on the same wages, by the Form 940 due date. Once you are excluded from the Oregon tax on your own wages, no state tax is paid on them, so that credit goes away and the federal tax on those wages goes up. Count that cost before you count the savings.
What do I keep in the file?
Do it once, do it right, and write it down. Someday an auditor, a lender, a buyer doing due diligence or an ex-spouse's lawyer will ask how your payroll accounts are set up and why. Have the answer in one place.
- A copy of the Form 2578 you filed, with the date.
- The Employment Department's written approval, showing the quarter it took effect.
- A line in your corporate minutes recording the election and the reason.
- A note to revisit it if anyone else becomes an owner or officer.
This could have been avoided.
It takes one form and one folder. Would it be a bad idea to check that yours are in place before the next payroll? Start with the Stop the Tax Leaks Scorecard. If the timing fits, book a Right Fit Call.
Where can you check these rules yourself?
- Employment Department: Form 2578, Corporate Officer Exclusion Request
- Employment Department: UI PUB 208, unemployment insurance for corporations and LLCs
- Employment Department: Tax forms and reports
- Employment Department: Tax frequently asked questions
- IRS Topic 759: Form 940 and FUTA tax
The stories on this page are composites. They are inspired by real situations, but names, facts and details have been changed.
This page is general information, not tax, legal or investment advice for your situation. Reading it does not create a client relationship. Tax law changes often, so check the current rules with a qualified professional before you act. See our disclaimer.